In a report published on November 18, 2026, TD Cowen maintained its Buy rating and $13 price target for Ethereum treasury company Sharplink (SBET). The firm took a more conservative view of ether’s price path, while assessing Sharplink’s active treasury management positively.
More activity, less ETH burned per transaction
Senior analyst Lance Vitanza said Ethereum network activity continued to grow, but a sharp decline in ETH burned per transaction prompted TD Cowen to temper its outlook. The firm assumed ether would end the fourth quarter of 2026 at approximately $2,413, down 10% from the third quarter, followed by a flatter appreciation path.
Staking and treasury holdings
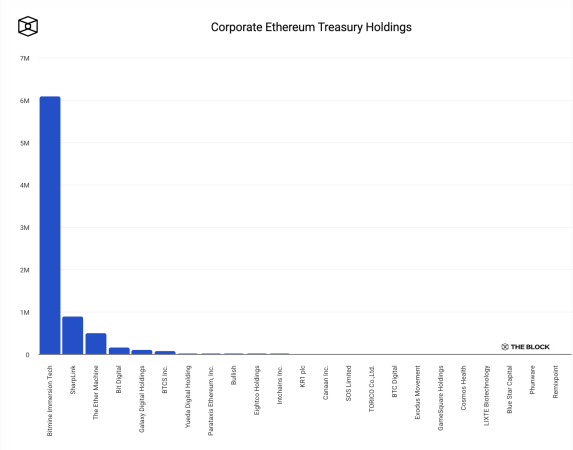
Sharplink held 896,003 ETH as of November 16, up from 892,708 ETH at the end of the third quarter. The recent increase came primarily from staking rewards and related yield rather than new purchases; cumulative staking rewards reached 31,820 ETH. The company had also allocated $200 million to liquid staking through Lido and deployed capital into the Galaxy Sharplink Onchain Yield Fund.
TD Cowen viewed those initiatives as potential sources of additional ETH-denominated returns but said it had largely left that potential upside out of its model. Vitanza said Sharplink could substantially outperform spot ether exchange-traded products in a favorable ether price environment by increasing ETH holdings per fully diluted share. If ether’s price remained depressed, he expected staking yield to more than cover operating costs. Those were the analyst’s projections, not reported outcomes.
Sharplink reported third-quarter net income of $751.4 million, or $3.45 per diluted share, compared with $104.3 million a year earlier. The result was driven largely by $676.7 million in unrealized gains on its ether holdings. Revenue rose 24% year over year to $13.5 million, including $13.1 million in staking income. CEO Joseph Chalom said the company was focused on maximizing the productivity of its ETH holdings while maintaining disciplined capital allocation.